Gambling Tax Deduction Rules: Why Itemizing Matters
How shifting IRS guidelines and digital reporting trends impact the financial reality of casual and frequent bettors.
The excitement of a winning ticket at the window often masks the complex financial reality that follows the celebration. As the 2026 Triple Crown season approaches, many Americans find themselves navigating a modernized landscape of digital wagering and instantaneous reporting. Understanding how these windfalls interact with the broader tax system is no longer just a concern for the high-stakes professional; it is a fundamental part of modern financial literacy for any casual participant.
The Internal Revenue Service (IRS) maintains strict protocols for how windfalls are categorized, often contrasting with how individuals perceive their “net” gains at the end of a weekend. While a win feels like a singular event, the financial lifecycle of that money involves specific reporting thresholds and documentation requirements. This article explores the current environment of gambling tax deduction rules, the nuances of reporting, and the behavioral trends defining how Americans manage these specific financial influxes.
The Intersection of Luck and Liability
For many households, a significant win on a trifecta or a sports parlay represents a “bonus” to the family budget, yet the IRS views this income with the same gravity as traditional wages. Federal law requires that all gambling winnings be reported as “Other Income” on Form 1040. This includes everything from lottery payouts and horse racing to the fair market value of non-cash prizes like cars or vacations.
The IRS gambling income threshold serves as the primary trigger for official documentation. Generally, for horse racing, a payer must issue a Form W-2G if the winnings are at least $600 and at least 300 times the amount of the wager. In a digital age where mobile betting apps have streamlined the wagering process, these triggers are more automated than ever, leaving a digital trail that ensures high levels of compliance and data accuracy for the 2026 tax filing season.
Financial behaviorists have noted a shift in how taxpayers perceive these winnings. Rather than viewing a $1,200 payout as a gross sum, many are beginning to account for the automatic 24% federal withholding that often applies to larger scores. This “net-of-tax” thinking is a sign of increasing financial sophistication among casual bettors who wish to avoid a surprise liability when they file their returns.
Navigating Gambling Tax Deduction Rules in a High-Standard Deduction Era
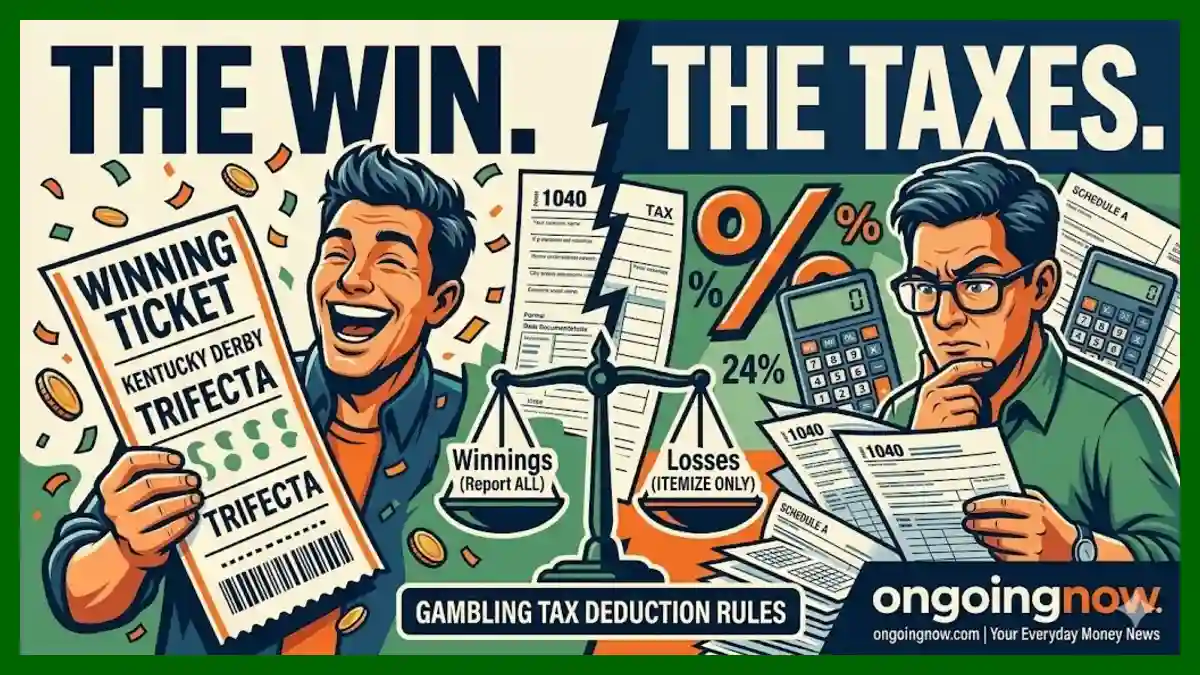
One of the most significant hurdles for the average taxpayer is the mechanism for offsetting wins with losses. Under current gambling tax deduction rules, you cannot simply subtract your losses from your wins and report the difference. Instead, the IRS requires that you report the full amount of your winnings as income.
To deduct your losses, you must choose to itemize your deductions on Schedule A. For a vast majority of Americans, the standard deduction—which has seen inflationary increases through 2026—is higher than their total itemized expenses. This creates a situation where a taxpayer might pay taxes on the full amount of a win even if they lost an equal amount over the course of the year.
The decision to itemize is a significant financial “fork in the road.” It requires comparing the total of your gambling tax deduction rules eligibility, mortgage interest, state and local taxes, and medical expenses against the standard deduction. For many, the math simply doesn’t favor itemization, meaning their gambling “business” is taxed on revenue rather than profit.
Why Reporting Horse Racing Winnings is More Transparent in 2026
The tradition of the Kentucky Derby brings with it a specific set of financial considerations. Reporting horse racing winnings has become more complex as “exotic” bets like Superfectas and Pick 6s gain popularity. These high-odds wagers frequently cross the 300-to-1 payout ratio, triggering immediate W-2G filings.
The evolution of parimutuel wagering technology has increased the speed of data sharing between tracks and the IRS. This real-time reporting means that the “paper trail” is established the moment the ticket is scanned for payout. For the bettor, this underscores the importance of maintaining a contemporaneous log of all activity, a practice that the IRS officially recommends but many taxpayers overlook.
The Kentucky Derby tax guide for the modern era isn’t just about the Churchill Downs winner’s circle; it’s about the millions of people wagering through ADW (Advance Deposit Wagering) platforms. These platforms provide year-end summaries, but the responsibility for accurate reporting remains with the individual. In the 2026 economy, where every dollar of adjusted gross income can affect eligibility for other tax credits, the accuracy of these reports is paramount.
The Financial Logic of Itemizing Gambling Losses
For those who do choose to itemize, itemizing gambling losses is subject to a hard cap: you cannot deduct more in losses than you have reported in winnings. You cannot use a “bad year” at the track to reduce your taxable income from your day job. This “basket” approach isolates gambling activity within the tax code.
To sustain a deduction during an audit, the IRS expects a high level of record-keeping. This includes:
The date and type of specific wagers.
The name and address of the gambling establishment.
The names of other people present at the time.
The amounts won and lost, supported by receipts, tickets, or statements.
This level of detail is a significant behavioral barrier. Most people do not treat their recreational activities with the rigor of a small business, yet gambling tax deduction rules essentially demand that they do if they wish to mitigate their tax burden. This disconnect often leads to taxpayers missing out on legitimate deductions simply because they lack the “proof” required by 2026 standards.
Professional Gambler Tax Status: A Different Financial Path
There is a distinct segment of the population that seeks to be classified under professional gambler tax status. For these individuals, gambling is not a hobby but a trade or business. This allows them to report their activity on Schedule C, potentially allowing them to deduct business expenses like travel, data subscriptions, and home office costs.
However, the “Hobby Loss” rules remain a primary area of focus for the IRS. To qualify as a professional, one must demonstrate a profit motive and carry out the activity in a businesslike manner. If the IRS deems the activity a hobby, the taxpayer loses the ability to deduct expenses beyond their winnings and must revert to the itemization rules on Schedule A.
This distinction is a major point of consideration for the growing number of “semi-pro” bettors in the sports-wagering era. The trade-off involves paying self-employment tax on net winnings in exchange for the ability to deduct related business expenses. It is a calculation that requires a deep dive into one’s long-term financial goals and risk tolerance.
Understanding State Taxes on Gambling and Offshore Implications
While federal rules provide a baseline, state taxes on gambling vary wildly and can significantly alter the “take-home” value of a win. Some states, like Nevada, have no state income tax, meaning the federal slice is the only concern. Others may tax winnings as ordinary income but do not allow for the deduction of losses at the state level, creating a “double hit” for the bettor.
The rise of digital platforms has also brought offshore betting tax laws back into the spotlight. Many bettors mistakenly believe that winnings from sites based outside the U.S. are “tax-free.” In reality, the IRS requires the reporting of worldwide income. Furthermore, maintaining significant funds in offshore accounts may trigger FBAR (Report of Foreign Bank and Financial Accounts) filing requirements, which carry heavy penalties for non-compliance.
In 2026, the global nature of financial data exchange means that “hidden” income is increasingly visible to domestic authorities. Consumers are finding that the safest financial path is one of total transparency, regardless of where the server for their favorite betting app is located.
Financial Insight: The “Winner’s Anxiety” Trend
Recent consumer surveys indicate a rising trend of “winner’s anxiety”—a phenomenon where individuals who receive a large windfall feel a sense of financial paralysis due to the complexity of the tax code. This behavior reflects a growing awareness of YMYL (Your Money, Your Life) topics and a desire for stability over speculation.
People are increasingly seeking out 2026 tax filing tips long before April, reflecting a proactive shift in financial behavior. Instead of spending a windfall immediately, many are setting aside the estimated tax portion in high-yield savings accounts. This shows a transition from “windfall spending” to “integrated financial management.”
What to Consider: A Comprehensive Breakdown
When reflecting on the role of gambling in a personal financial plan, several trade-offs and considerations emerge:
The Itemization Hurdle: Consider whether your total deductions will actually exceed the standard deduction. If not, every dollar won is taxed at your top marginal rate, regardless of losses.
Withholding vs. Liability: Remember that the 24% withheld by a casino or track is just an estimate. Depending on your total annual income, you may owe more—or be entitled to a refund—when you file.
The Impact on Credits: Large wins increase your Adjusted Gross Income (AGI). A higher AGI can phase out eligibility for student loan interest deductions, child tax credits, or medical expense thresholds.
The Specifics of Payouts: The tax on trifecta payouts or other high-multiplicity bets is often handled differently at the source than a standard “to win” bet. Always check the paperwork provided at the time of payout.
State-Level Disparities: Research your specific state’s stance on gambling losses. A federal deduction does not guarantee a state-level one.
Key Takeaways
All gambling winnings are legally reportable as income, regardless of the amount or where they were won.
The IRS gambling income threshold ($600 for many events) triggers a W-2G, but smaller wins are still taxable.
Losses can only be deducted if you itemize on Schedule A and are capped at the amount of your winnings.
Digital and offshore wagering are subject to the same reporting requirements as domestic, physical casinos.
A significant win can increase your AGI, potentially impacting other tax benefits and credits.
The landscape of gambling and taxes is no longer a niche corner of the financial world. As digital access expands and the IRS streamlines its data collection, the “casual” bettor must adopt the mindset of a diligent record-keeper. Understanding the gambling tax deduction rules is about more than just compliance; it is about protecting your overall financial health from the volatility of a winning streak.
This is for informational purposes only and not personalized financial advice. Consult a licensed professional for your specific situation.
Stay sharp with Ongoing Now!
Source and Data Limitations: This article is based on IRS publications (including Publication 529 and 525), 2026 tax bracket projections from reputable fiscal policy centers, and consumer behavior reports regarding the sports betting industry’s growth. Data on state-level tax variations is sourced from official state revenue departments. Note that tax laws are subject to legislative changes, and “2026” figures refer to the tax year for which returns are typically filed in early 2027. This content does not account for specific municipal taxes or international treaties that may apply to non-residents.