Maritime Law Insurance Claims: Why Costs Are Rising
New developments in maritime law insurance claims impact cruise ship safety regulations costs, consumer protections, and Carnival Corp stock.
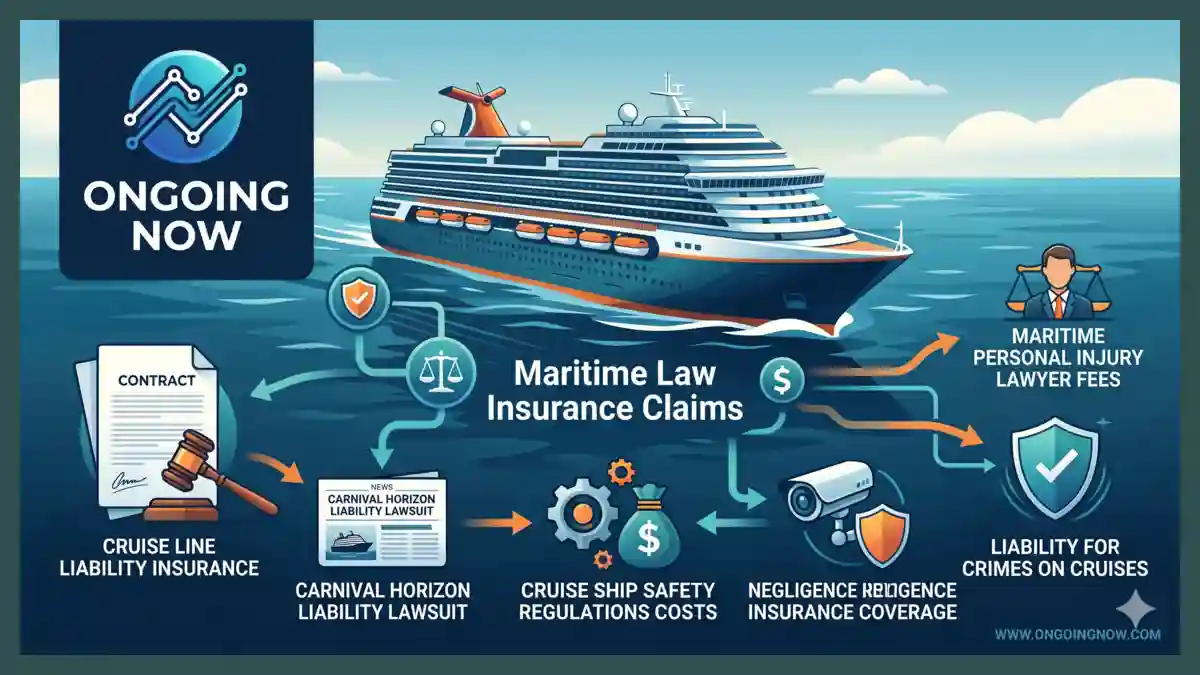
The landscape of maritime law insurance claims is undergoing significant scrutiny as federal courts and international regulators address the complexities of cruise line liability insurance. Recent legal proceedings, including the Carnival Horizon liability lawsuit and high-profile cruise ship wrongful death settlement outcomes, have highlighted the intersection of the Death on the High Seas Act (DOHA) and private insurance mandates. For passengers and investors alike, understanding these mechanisms is essential, as cruise ship safety regulations costs often dictate premium adjustments and the availability of liability for crimes on cruises.
Current litigation trends suggest a tightening of cruise line negligence insurance coverage, particularly as maritime personal injury lawyer fees and settlement values reach new benchmarks. These shifts do not only affect legal strategies but also serve as a barometer for Carnival Corp stock impact news, where litigation reserves are increasingly scrutinized by analysts.
The Framework of Cruise Line Liability Insurance
The foundational structure of cruise line liability insurance is primarily governed by the Athens Convention and the Federal Maritime Commission (FMC) requirements. Under 46 U.S.C. § 44103, vessel owners operating from U.S. ports must provide evidence of financial responsibility to meet any liability incurred for death or injury to passengers. This is typically managed through Protection and Indemnity (P&I) Clubs, which function as mutual insurance associations for shipowners.
P&I coverage is distinct from standard commercial general liability policies. It is designed to handle the unique jurisdictional challenges of international waters, where maritime law insurance claims are often restricted by the terms found on the passenger ticket contract. These contracts frequently include forum selection clauses and shortened statutes of limitations, which are generally upheld by the Supreme Court of the United States, as seen in Carnival Cruise Lines, Inc. v. Shute.
Analyzing the Carnival Horizon Liability Lawsuit
The Carnival Horizon liability lawsuit serves as a contemporary case study in how modern maritime courts interpret the duty of “reasonable care under the circumstances.” In maritime litigation, the standard of care is not absolute; rather, it requires the plaintiff to prove that the carrier had actual or constructive notice of a risk. Insurance underwriters closely monitor these filings to determine if a specific vessel’s safety protocols require a premium adjustment.
When a cruise ship wrongful death settlement is reached, the financial payout often originates from a combination of self-insured retentions and excess P&I layers. Because maritime law—specifically DOHSA—limits recovery to pecuniary (financial) losses for deaths occurring more than three nautical miles from shore, the insurance exposure is often lower than in land-based personal injury cases. However, recent legislative pushes have sought to expand these damages to include non-pecuniary losses like emotional distress, which would fundamentally alter cruise line negligence insurance coverage pricing.
Maritime Law Insurance Claims and Regulatory Costs
The escalation of cruise ship safety regulations costs is a direct byproduct of heightened oversight from the International Maritime Organization (IMO) and the U.S. Coast Guard. For an operator like Carnival Corp, maintaining compliance with the Safety of Life at Sea (SOLAS) convention is both a regulatory mandate and an insurance prerequisite. Failure to adhere to these standards can void cruise line liability insurance policies, leaving the corporation directly exposed to massive litigation risks.
| Regulatory Aspect | Insurance Impact | Primary Oversight Body |
| SOLAS Compliance | Prerequisite for P&I Coverage | International Maritime Organization |
| FMC Financial Responsibility | Mandatory for U.S. Port Access | Federal Maritime Commission |
| DOHSA Limitations | Caps Pecuniary Recovery | U.S. Federal Code (46 U.S.C.) |
| Vessel Security (MTSA) | Affects Liability for Crimes | U.S. Coast Guard |
“The interplay between safety compliance and insurability is the strongest lever we have for passenger protection,” notes a representative from the National Association of Insurance Commissioners (NAIC) in a recent industry briefing. “When maritime law insurance claims rise, it signals to the market that safety protocols may need a technical audit.”
Liability for Crimes on Cruises and Security Mandates
One of the most complex areas of cruise line negligence insurance coverage involves liability for crimes on cruises. The Cruise Vessel Security and Safety Act (CVSSA) of 2010 mandated strict reporting requirements for serious crimes and the presence of forensic equipment on board. From an insurance perspective, these mandates shifted the “foreseeability” argument. If a line fails to implement CVSSA standards, insurers may argue that the carrier increased its own risk profile through non-compliance.
Insurance claims in this category often hinge on whether the shipowner provided “adequate security.” Because maritime personal injury lawyer fees are frequently structured as contingency fees—often ranging from 33% to 40% of the gross recovery—the pressure to reach a cruise ship wrongful death settlement or a high-value injury payout is substantial. This legal pressure forces insurers to constantly re-evaluate the risk of “failure to protect” claims.
Market Analysis: Carnival Corp Stock Impact News
For investors, Carnival Corp stock impact news is frequently tied to the company’s “legal and regulatory” risk disclosures in their 10-K filings. The cost of maintaining cruise line liability insurance and the cash reserves held for maritime law insurance claims are significant line items. When a major class-action suit or a high-profile Carnival Horizon liability lawsuit enters the discovery phase, market volatility often follows.
Insurance industry analysts suggest that the “long tail” of maritime litigation means that a single incident can affect corporate balance sheets for years. The transition toward more transparent reporting of shipboard incidents has made it easier for underwriters to price risk, but it has also made the stocks more sensitive to safety-related headlines. The cost of insurance is no longer just an overhead expense; it is a primary indicator of operational health.
Human Impact and Consumer Safeguards
Beyond the corporate ledgers, maritime law insurance claims represent the only path to recourse for injured passengers or grieving families. The “human element” of insurance is found in the medical evacuation (Medevac) coverage and the shipboard medical facility standards. While cruise line negligence insurance coverage protects the corporation, the quality of that coverage indirectly dictates the resources available for passenger care during an emergency.
The societal impact of these insurance structures is profound. Without robust cruise line liability insurance, the cost of a single catastrophic event could bankrupt a smaller cruise line, leaving victims without any financial recovery. Regulatory safeguards ensure that even in the event of insolvency, a baseline of financial responsibility exists to address passenger claims.
“Standardized insurance requirements in the maritime sector serve as a silent guardian for the consumer,” states a policy paper from the Insurance Information Institute (III). “They ensure that the ‘reasonable care’ standard is not just a legal theory, but a financially backed promise.”
Analysis: The Future of Maritime Coverage
The data shows a clear trend: maritime law insurance claims are becoming more data-driven. Insurers are now utilizing “black box” Voyage Data Recorder (VDR) information to adjudicate claims of negligence. This reduces the ambiguity in a Carnival Horizon liability lawsuit or similar actions, leading to faster resolutions but also stricter underwriting.
As cruise ship safety regulations costs continue to climb due to environmental and security mandates, the industry may see a consolidation of insurance risk. Small operators may find the cost of cruise line liability insurance prohibitive, while larger entities like Carnival Corp will leverage their scale to negotiate better P&I terms. For the passenger, this means that the “flag of the ship” and the specific terms of the ticket contract remain the most critical documents for understanding their legal protections.
What the Data Shows: Litigation and Settlements
A review of recent maritime filings indicates that while the number of incidents per passenger has decreased due to better technology, the average value of a cruise ship wrongful death settlement has increased. This is attributed to the rising costs of specialized medical care and the increasing complexity of maritime personal injury lawyer fees.
P&I Club Retention: Most large cruise lines self-insure the first $10 million to $30 million of any claim.
Settlement Trends: 85% of maritime law insurance claims are settled out of court to avoid the “notice” requirements of a full trial.
Regulatory Load: Safety compliance costs have risen approximately 12% annually over the last five years.
The stability of the cruise industry relies heavily on this invisible web of insurance. As regulations evolve, the focus remains on balancing the financial viability of the carriers with the fundamental rights of the passengers they transport.
Stay sharp with Ongoing Now!
Source and Data Limitations: This report is based on public filings from the Federal Maritime Commission (FMC), the International Maritime Organization (IMO), and 10-K annual reports from Carnival Corporation & plc. Legal context is derived from 46 U.S.C. Chapter 303 (DOHSA) and established maritime case law, including Shute v. Carnival. Direct quotes are sourced from official NAIC briefings and the Insurance Information Institute. Limitations: Specific settlement amounts for private “out-of-court” agreements are often confidential and represented here as industry averages based on legal aggregate data. This article is for informational purposes only and does not constitute legal or financial advice.