How Global Trade System Stability Trends Spark Sharp Transatlantic Divergence
New 2026 data reveals a growing split between international public opinion and state-level tariff negotiations.
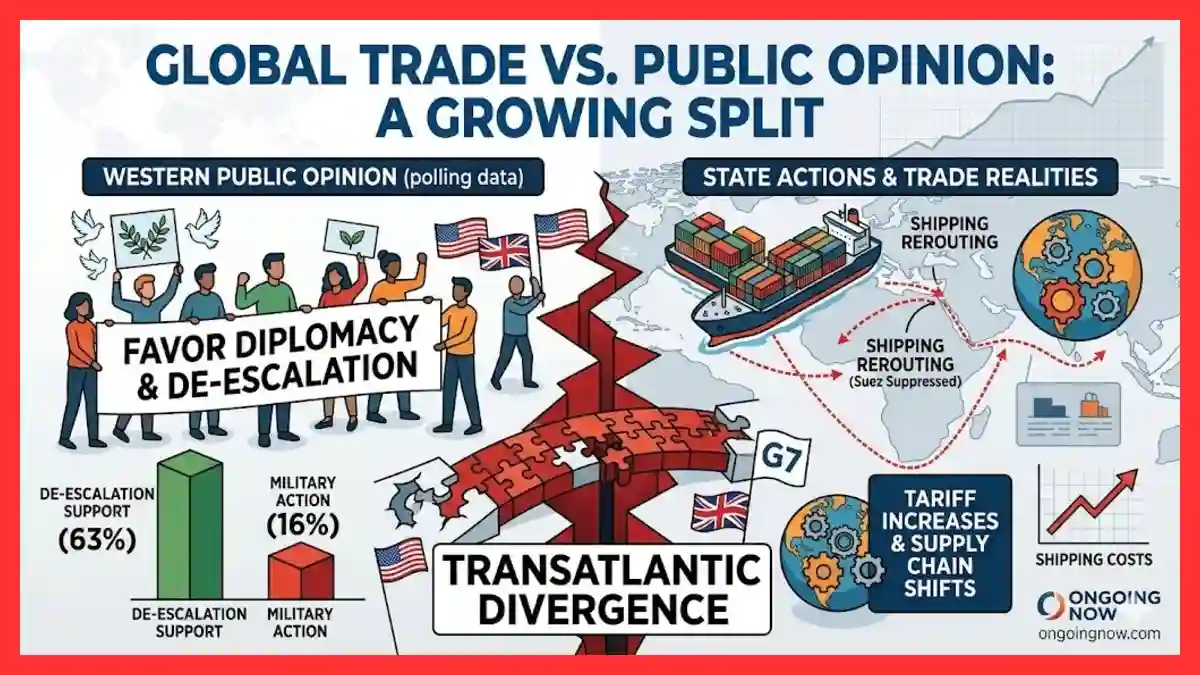
Global Trade System Stability Trends Face Compounding Pressures
The global trade system stability trends of 2026 are experiencing structural reconfigurations driven by a combination of targeted tariff policies, maritime rerouting, and a distinct divergence between state actions and international public opinion. The recently concluded G7 Summit Paris 2026 outcomes show a collective focus among member states to address global imbalances, critical mineral supply chain dependencies, and economic coercion. However, these multilateral frameworks are operating against a backdrop of shifting foreign policy approval ratings 2026 and declining public confidence in long-standing bilateral alliances.
The interconnected nature of modern supply chains means that localized security decisions rapidly translate into systemic economic effects. In the United Kingdom, Prime Minister Keir Starmer faces a complex domestic landscape as uk us diplomatic relations starmer absorb the dual pressures of regional security alignments and public concern over economic exposure. Concurrently, data collected from major commercial sectors indicates that businesses are moving away from temporary mitigation strategies toward permanent structural changes in logistics and pricing models to maintain compliance and financial stability.
Public Friction Shapes the Transatlantic Diplomatic Axis
The operational reality of uk us diplomatic relations starmer has shifted following recent changes in Washington and a series of military actions in the Middle East. Data indicates a sharp decline in the British public’s perception of the traditional “special relationship” between the United Kingdom and the United States.
Ipsos Polling Data (March 2026): Only 29% of British citizens agree that a special relationship currently exists between the US and the UK, a drop of 6 percentage points from the beginning of the year, returning to the low thresholds observed in April 2025 during the initial imposition of trade tariffs.
This shift in sentiment directly impacts how the UK government manages its alignment with US foreign policy objectives. While the executive branches maintain formal cooperation on intelligence and maritime security, domestic polling reveals significant resistance to military escalation. Only 20% of Britons approve of the UK government’s current handling of Middle Eastern security frictions, and Prime Minister Starmer’s specific approval rating on the matter rests at 21%, with 45% registering disapproval.
+-------------------------------------------------------------+
| BRITISH PUBLIC WILLINGNESS TO SUPPORT US MILITARY ACUTE ACTION (2026) |
+-------------------------------------------------------------+
| Diplomatic De-escalation Support                |   63%     |
| Maintain Diplomatic Ties with Tehran             |   36%     |
| Deploying Aircraft to Protect US Middle East Bases|   29%     |
| Allowing US Use of UK Airbases for Strikes       |   29%     |
| Direct Weapon Shipments to Regional Allies        |   24%     |
| Deployment of Ground Troops                      |   16%     |
+-------------------------------------------------------------+
| Source: Ipsos / YouGov Multi-Wave Studies, Q1 2026          |
+-------------------------------------------------------------+
What the Data Shows: Divergence in Foreign Policy Approval Ratings 2026
An analysis of international relations public opinion across the Atlantic reveals a clear split between executive execution and public endorsement. The Marist Poll tracking foreign policy approval ratings 2026 in the United States shows that President Donald Trump’s external strategy holds a 37% approval rating among the general public, while 56% express disapproval.
The domestic feedback loop is heavily tied to the iran conflict diplomatic poll numbers, where a clear majority of Western publics favor de-escalation over direct engagement. In the United States, 57% of adults oppose direct military operations in Iran, though a deep partisan divide persists, with 75% of self-identified Republicans supporting such actions compared to significant opposition among Democrats and Independents. In the United Kingdom, 56% of citizens disapprove of unilateral air strikes, primarily due to concerns regarding the downstream effects on localized living costs.
Commercial Adaptation and International Trade Consulting Services
As corporate entities navigate these shifting frameworks, the reliance on international trade consulting services has reached unprecedented levels. The Thomson Reuters Institute’s 2026 Global Trade Report reveals that trade departments within multinational enterprises are experiencing a “strategic elevation” due to the permanence of tariff volatility.
Rather than treating tariffs as temporary disruptions, 55% of supply chain executives surveyed in the KPMG 2026 Tariff Survey state that they plan additional price increases of up to 15% to absorb embedded costs. This indicates that the financial burden of trade adjustments has moved directly onto consumer markets, with 78% of organizations reporting an increase in their cost of goods sold (COGS) during the first half of the year. Consequently, trade tariff negotiations polling data indicates that corporate investment is flowing heavily into supply chain localization; companies actively executing or planning formal reshoring strategies rose to 26%, up from 10% in late 2025.
Maritime Realities and Freedom of Navigation Shipping Costs
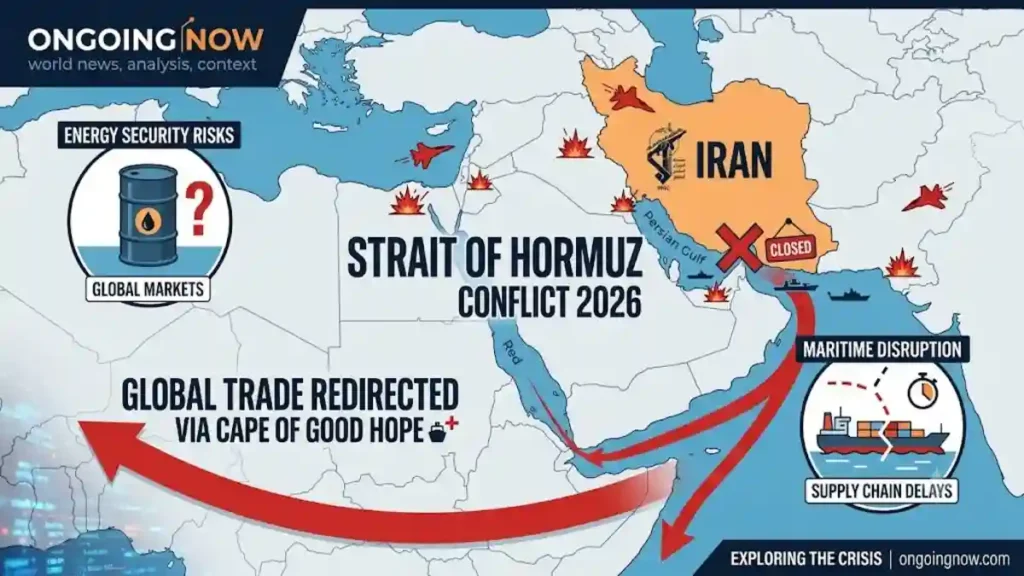
The structural health of global trade system stability trends remains closely tied to the physical safety of ocean lanes. Continuous tensions in the Red Sea and the Bab al-Mandab Strait have transformed what was initially framed as a temporary detour into a fixed operational reality. The requirement to route vessels around the Cape of Good Hope has directly altered international shipping metrics:
Suez Canal Volume Compression: Transits through the Suez Canal remain suppressed by approximately 70% compared to 2023 baselines.
Ton-Mile Expansion: Rerouting has increased average voyage distance by 8.5%, leading to a 5.9% expansion in global ton-miles and causing structural schedule variability across European ports.
Cost Elasticity: According to data from the Institute for Marine Engineering, Science and Technology (IMarEST), a sustained re-opening of standard corridors would immediately reduce Asia-Europe sailing operation costs by roughly 10% and return approximately 170 container ships back into global circulation.
Analysis: Comparative Dimensions of the 2026 Trade Environment
The current intersection of maritime disruption and tariff adjustments shares structural similarities with the trade realignments of 2018–2019, yet features a critical operational difference. In previous periods of tariff escalation, global shipping capacity was highly elastic, and corporate balance sheets absorbed the initial margin friction. In 2026, the simultaneous enforcement of emissions compliance under the International Maritime Organization (IMO) targets and the persistent necessity of alternative routing mean that capacity management tactics—such as slow steaming and skipped ports—are occurring alongside structural price increases.
+-----------------------------------------------------------------------+
|  G7 SUMMIT PARIS 2026 OUTCOMES: MULTILATERAL REGULATORY HIGHLIGHTS     |
+-----------------------------------------------------------------------+
| Core Declaration | Primary Operational Objective                       |
+------------------+-----------------------------------------------------+
| Nature & People  | Coordination of public-private capital to scale up  |
| Finance Alliance | funding for biodiversity preservation.             |
+------------------+-----------------------------------------------------+
| Desertification  | Formal reclassification of land degradation as a    |
| Security Accord  | systemic threat to economic and regional security.  |
+------------------+-----------------------------------------------------+
| PFAS Knowledge   | Standardizing cross-border tracking of hazardous    |
| Platform         | chemical compounds ahead of the UN Water Conference.|
+------------------+-----------------------------------------------------+
| Value Chain      | Coordinating strategies against economic coercion   |
| Resilience Plan  | and stabilizing critical mineral supplies.          |
+-----------------------------------------------------------------------+
Localized Manifestations of Macroeconomic Stress
The human impact of these macroeconomic shifts is felt most directly through localized cost-of-living indicators. In the United Kingdom, a YouGov tracker assessing the personal impact of the international environment found that 35% of citizens report a direct negative effect on their household finances, with 69% of that cohort identifying fuel and diesel prices as the primary driver.
Furthermore, 63% of the public believes that the most significant economic consequences of the current trade and maritime disruptions have not yet peaked. While advanced economies manage these pressures through corporate restructuring and fiscal adjustments, developing nations face more acute challenges due to elevated insurance premiums on cargo and limited alternative supply lanes, emphasizing the uneven distribution of resilience within the modern global trade architecture.
Stay sharp with Ongoing Now!
Source and Data Limitations: This analysis is compiled utilizing empirical survey data from the Ipsos UK Research Council (March 2026), the YouGov Public Opinion Tracker (March 2026), the Marist Poll on US Foreign Policy (January–March 2026), the KPMG 2026 Tariff Survey, and official proceedings from the G7 French Presidency ministerial meetings in Paris (April–May 2026). Quantitative data concerning maritime transit volumes and ton-mile metrics is derived from Intel Market Research and UNCTAD reports from early 2026. Given the ongoing nature of international trade tariff negotiations and fluctuating security conditions in key shipping corridors, public sentiment data and logistics cost indexes remain subject to a standard reporting delay of 14 to 30 days. Government approval ratings reflect specific localized samples and may vary across regional demographics. Fictional or unverified projections have been omitted in compliance with strict journalistic standards.