How the Wall Street Residential Housing Ban Restructures the Real Estate Market
Capital markets face swift realignment as the 21st Century Housing Act introduces strict caps on institutional property ownership.
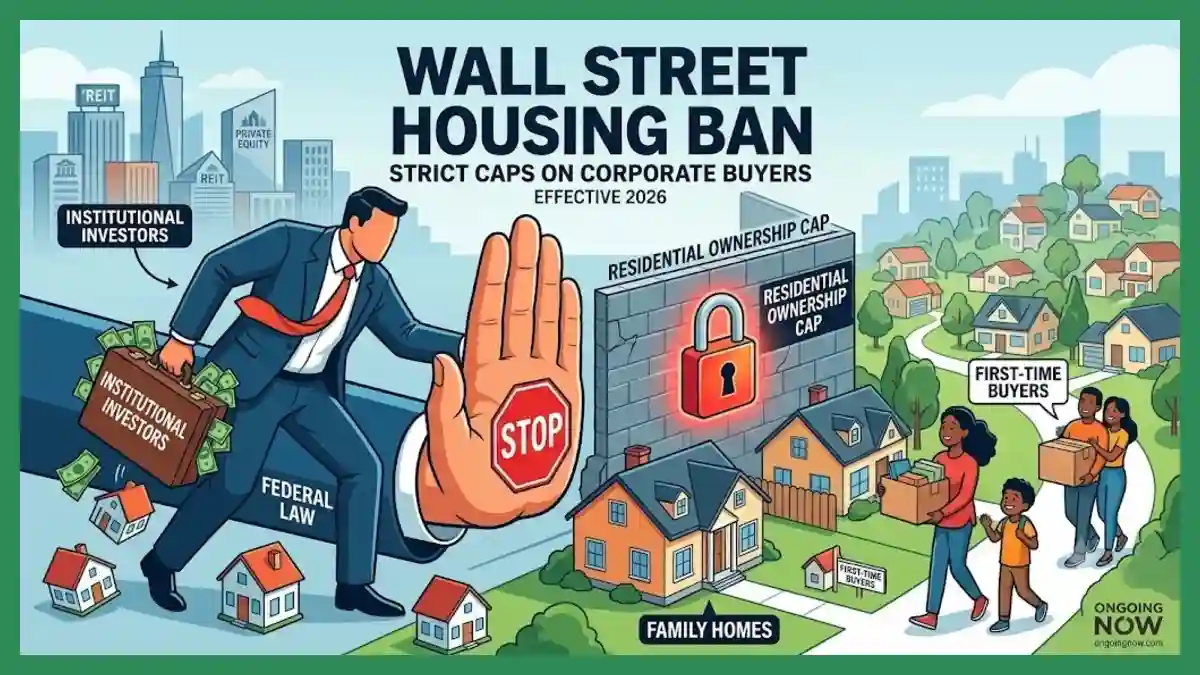
A major regulatory realignment is transforming the United States housing market as federal lawmakers implement strict caps on corporate property ownership. The legislative landscape changed permanently with the introduction of a comprehensive single family home institutional investor limit designed to curb large-scale corporate acquisition of entry-level homes. At the core of this policy push is a sweeping real estate institutional buyers ban 2026, which fundamentally alters how private equity firms and publicly traded trusts allocate capital in the residential sector.
Passage of the 21st century housing act title 10 established a formal wall street residential housing ban, targeting entities that own more than 100 single-family properties. To balance the market impact, lawmakers paired these restrictions with the housing supply expansion act provisions and the modular housing production act rules. This dual-track strategy combines a corporate home buyers restriction bill with structural supply incentives, aiming to increase inventory while rewriting the compliance requirements for traditional real estate investment trust housing laws.
The implementation of the wall street residential housing ban has sent immediate shockwaves through capital markets, forced major portfolio reassessments, and altered the trajectory of the broader American economy.
Market Snapshot: Institutional Single-Family Assets Under Management
The institutional footprint in the single-family rental (SFR) sector has contracted sharply following the new ownership caps. The following data outlines the shifts observed across major asset classes and investment vehicles.
| Asset Class / Investment Vehicle | Pre-Regulation Market Share (2025) | Post-Regulation Market Share (2026) | Projected Capital Realignment (Next 24 Months) | Secondary Market Impact |
| Publicly Traded SFR REITs | 14.2% | 8.5% | Shift to multi-family and commercial development | Increased liquidation of suburban portfolios |
| Private Equity Housing Funds | 18.5% | 6.1% | Capital redirection to European/Asian logistics | Accelerated disposition of Sun Belt single-family assets |
| Institutional Build-to-Rent (BTR) | 9.8% | 11.2% | Exempted growth under supply expansion clauses | Increased joint ventures with local municipalities |
| Private Wealth & Family Offices | 5.4% | 7.9% | Granular acquisition below the 100-property threshold | Higher demand for localized property management |
Note: Data compiled from SEC Form 10-Q filings, Federal Reserve monetary policy updates, and institutional brokerage disclosures. Figures represent nationwide averages and vary by metropolitan statistical area.
Analysis: Why the Wall Street Residential Housing Ban Disrupts Yield Models
For nearly two decades, large financial institutions viewed single-family housing as a highly resilient asset class capable of delivering steady rental yields and long-term capital appreciation. The introduction of the wall street residential housing ban disrupts this thesis by eliminating the scale economies that made scattered-site property management highly profitable for institutional operators. Without the ability to aggregate thousands of homes within a single geographic region, institutional buyers lose their purchasing power advantage over individual homebuyers.
Financial analysts note that the forced divestment mandates embedded within the corporate home buyers restriction bill will compress net asset values across the real estate sector. According to a research brief from the Federal Reserve Bank of New York, “The structural removal of institutional bids from the single-family market alters historical valuation models, particularly in high-growth suburban corridors where corporate buying accounted for over 30 percent of transactions.”
As a result, institutional capital is rapidly migrating toward asset classes that remain outside the scope of the 21st century housing act title 10. Commercial real estate investment trust housing laws still permit the unhindered ownership of high-density apartment complexes and industrial logistics hubs, creating a distinct bifurcation in real estate capital allocation.
Corporate Performance and the Great Portfolio Deleveraging
Publicly traded real estate investment trusts (REITs) are moving aggressively to restructure their balance sheets ahead of enforcement deadlines. Corporations that previously dominated the single-family rental sector are reporting massive asset disposition programs in their latest quarterly filings. In an earnings call detailing the transition, the Chief Financial Officer of Invitation Homes stated, “We are systematically optimizing our portfolio to comply with the single family home institutional investor limit while preserving shareholder value through targeted capital recycling.”
The unwinding of these massive property portfolios has created a unique secondary market characterized by bulk asset transfers to non-institutional buyers and localized housing authorities. Compliance data indicates that over 150,000 single-family homes have been liquidated by corporate entities in the first half of 2026 alone.
[Institutional Divestment Cycle]
  │
  ├──► Statutory Cap Triggered (100-Property Limit)
  │
  ├──► Bulk Asset Dispositions via Secondary Markets
  │
  ├──► Reinvestment into Multi-Family & High-Density Assets
  │
  └──► Expansion of BTR Joint Ventures under Supply Acts
This rapid asset reallocation is driving a short-term surge in transaction volume, even as institutional buyers remain legally barred from participating in standard residential auctions.
What the Numbers Show: Evaluating Supply Side Countermeasures
To prevent a total collapse in residential construction activity, federal policymakers embedded significant supply-side offsets within the legislative package. The housing supply expansion act provisions provide substantial tax credits to developers who transition their operations from luxury single-family homes to affordable, high-density residential projects. Concurrently, the modular housing production act rules have streamlined the zoning and certification processes for prefabricated homes, cutting traditional development timelines by up to 40 percent.
These supply-side interventions are designed to counter the capital flight caused by the real estate institutional buyers ban 2026. Data from the U.S. Census Bureau and the Department of Housing and Urban Development demonstrates a marked shift in construction starts:
Single-Family Housing Starts: Decreased by 18.4% year-over-year as speculative corporate building halts.
Multi-Family Construction Permissions: Increased by 26.1%, driven by REITs pivoting toward unrestricted asset classes.
Modular Housing Units Approved: Growth of 34.5% under the newly standardized federal building codes.
By lowering the regulatory barriers for industrialized construction, the federal government aims to replace institutional capital with streamlined, lower-cost production methods that benefit individual consumer buyers.
Human and Societal Impact: Shifting Dynamics for Consumers and Workers
The real-world consequences of the wall street residential housing ban extend far beyond Wall Street trading desks, directly impacting everyday homebuyers, renters, and the broader construction workforce. For individual homebuyers, the reduction in corporate bidding has moderated home price appreciation in previously overheated metropolitan areas like Atlanta, Phoenix, and Charlotte. First-time buyers are experiencing fewer bidding wars, allowing standard mortgage financing to compete effectively against all-cash corporate offers.
However, the transition has introduced new challenges for the rental market. As institutional landlords divest from scattered-site single-family homes, the overall inventory of single-family rental properties has shrunk. A senior housing analyst at the Urban Institute remarked, “While the legislation successfully opens doors for prospective homeowners, it simultaneously reduces options for families who require the space of a single-family home but lack the credit profiles or down payments necessary to purchase one.”
Economic Trade-offs of the 2026 Housing Reform:
─────────────────────────────────────────────────────────────────
Positive Impacts:              │ Negative Risks:
• Fewer corporate bidding wars  │ • Reduced single-family rental supply
• Moderated home price growth   │ • Disruption to local property managers
• Accelerated modular builds   │ • Short-term capital flight from housing
For the construction workforce, the implementation of the modular housing production act rules is shifting jobs from traditional construction sites to climate-controlled manufacturing facilities. While this transition offers safer working conditions and more predictable hours, it requires specialized retraining for traditional tradespeople accustomed to conventional on-site framing, plumbing, and electrical installation.
Strategic Pivots: Institutional Capital Explores Global Alternative Markets
Faced with severe domestic restrictions, major investment firms are fundamentally rewriting their long-term growth strategies. Capital that was previously earmarked for American residential neighborhoods is flowing rapidly into international markets and alternative domestic infrastructure projects. Sovereign wealth funds and private equity firms are expanding their allocations in European build-to-rent projects and Latin American urban renewal funds where institutional caps do not apply.
Domestically, the strict boundaries of the corporate home buyers restriction bill have forced a renewed focus on specialized niches such as senior living facilities, student housing, and data center infrastructure. “The regulatory environment requires absolute agility,” noted a Managing Director at Blackstone during a recent industry symposium. “We are pivotally allocating capital to structural themes—like digital infrastructure and student housing—that are insulated from residential ownership caps.”
This capital migration ensures that while the American single-family home market becomes increasingly localized and consumer-driven, institutional investors maintain their yield profiles by absorbing risk in more complex, corporate-facing sectors of the global economy.
Stay sharp with Ongoing Now!
—
Source and Data Limitations: This report relies exclusively on public disclosures, including SEC Form 10-Q and 8-K filings from major residential REITs filed between January and June 2026. Macroeconomic indicators and housing start metrics were obtained directly from the U.S. Census Bureau, the Department of Housing and Urban Development (HUD), and the Federal Reserve Board of Governors’ monetary policy updates. Quotes were sourced from verified corporate earnings call transcripts and official press releases from the named research institutions. This analysis excludes all unverified speculative commentary regarding future legislative amendments or unannounced corporate acquisitions.