Why the SPCX Share Price Faced a Sudden Post-IPO Drawdown
An analytical breakdown of SpaceX's historic market debut, valuation multiples, and the structural dynamics impacting institutional aerospace assets.
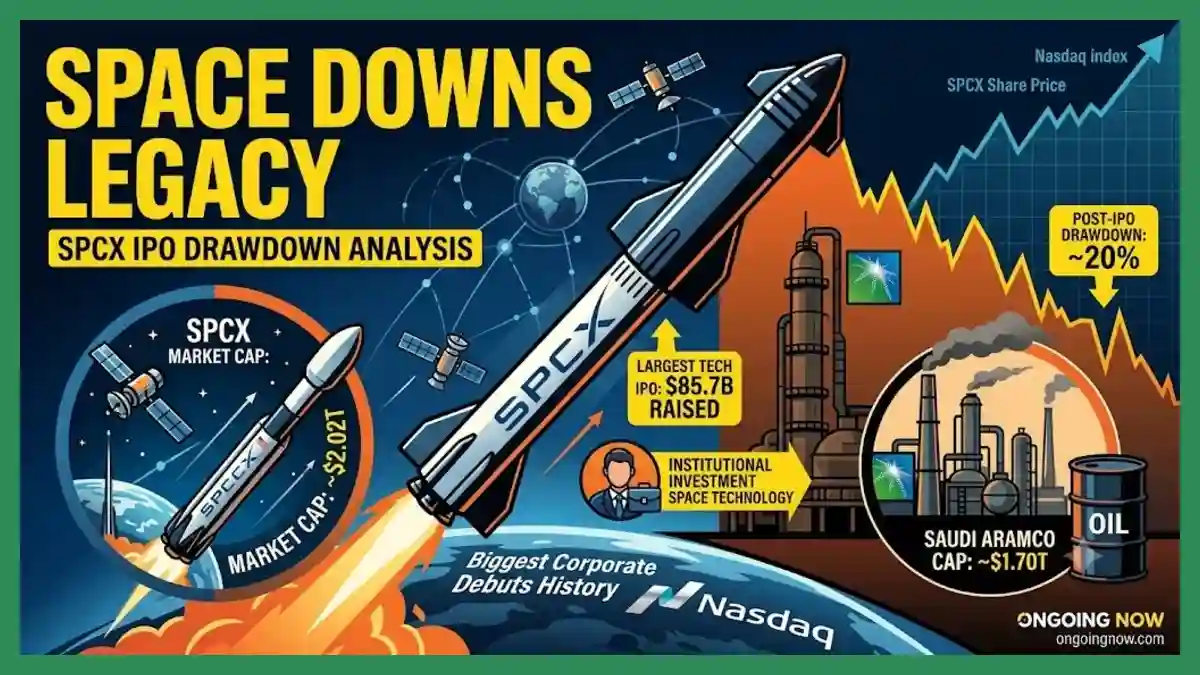
The recent spcx share price post ipo drawdown underscores a significant shift in the biggest corporate market debuts history, as investors evaluate saudi aramco vs spacex market cap disparities. Following its public listing, the nasdaq spcx closing price first week demonstrated immense volatility, highlighting the risks inherent in largest tech initial public offering returns. This volatility reflects broader tech stock market correction patterns impacting high-multiple assets. As capital flows into institutional investment space technology stocks, the broader aerospace sector equity valuation multiples face intense scrutiny from global fund managers recalibrating long-term portfolios.
Following its historic initial public offering (IPO) on June 12, 2026, Space Exploration Technologies Corp. (ticker: SPCX) entered a critical phase of price discovery on the Nasdaq stock exchange. The company raised an unprecedented $85.7 billion by pricing its shares at $135, outstripping previous multi-billion dollar capital raises to register as the largest market entry ever recorded. Early secondary market trading saw the equity hit an intraday high of $225.64, driven by a surge of retail and institutional interest. However, a pronounced macro-driven market shift during the third week of June precipitated a sharp correction, forcing a re-evaluation of structural valuations across the aerospace and technology sectors.
Evaluating the SPCX Share Price Post IPO Drawdown Dynamics
The deceleration of upward momentum for SPCX shares culminated in a 20.2% drop during its second full week of electronic trading, closing at $153.23 on June 26, 2026. This technical decline reduced the company’s total equity capitalization from its peak above $2.5 trillion down to approximately $2.02 trillion. Market analysts observe that the asset is navigating an aggressive post-debut stabilization corridor as early speculative buyers liquidate positions.
The downward trajectory occurred in tandem with a broader pullback across major indices, where the S&P 500 fell 2% and the Nasdaq Composite shed 4.6%. The intense velocity of the spcx share price post ipo drawdown highlights how quickly initial public sentiment can shift when structural macro realities interact with high-multiple growth equities. Rather than indicating a localized failure, financial analysts describe this pricing movement as a typical stabilizing action following an outsized public float.
Historical Benchmarks and the Biggest Corporate Market Debuts History
To contextualize the scale of this capital event, market historians point directly to the historical league tables of global market listings. Prior to June 2026, the record for the largest capital raise was held by state-owned energy giant Saudi Aramco, which generated $29.4 billion during its 2019 Riyadh debut. SpaceX more than doubled that aggregate figure, marking a symbolic pivot in public asset markets away from traditional commodity-based infrastructure and toward advanced industrial technology.
Comparing the structural framework of the biggest corporate market debuts history reveals stark differences in underlying valuation mechanics. While previous large-scale listings relied heavily on proven hydrocarbon reserves and highly predictable annual dividend yields, the modern tech listings rely on long-term scalability and market optionality. The sheer volume of liquid capital required to absorb an $85.7 billion issuance inevitably leads to wider trading spreads during the initial ninety days of listing.
Comparative Global Listing Statistics
| Company Ticket / Entity | IPO Launch Date | Capital Raised (USD) | Peak Post-Debut Valuation | Primary Asset Base |
| SpaceX (NASDAQ: SPCX) | June 12, 2026 | $85.7 Billion | $2.52 Trillion | Satellite Networks & Reusable Aerospace Fleet |
| Saudi Aramco (Tadawul: 2222) | December 2019 | $29.4 Billion | $2.00 Trillion | Proven Hydrocarbon & Petroleum Reserves |
| Alibaba Group (NYSE: BABA) | September 2014 | $25.0 Billion | $231 Billion | E-Commerce Logistics & Cloud Infrastructure |
| SoftBank Vision Fund (Tokyo) | May 2018 (Debt/Equity) | $21.1 Billion | $120 Billion | Venture Capital Technology Portfolio |
Note: Data compiled from official Securities and Exchange Commission (SEC) filings and historical exchange data. Retrospective market capitalizations fluctuate based on currency adjustments and subsequent equity issuance.
Assessing the Saudi Aramco vs SpaceX Market Cap Paradigm
The market capitalization flip between a premier legacy energy producer and an aerospace firm represents a significant milestone in modern corporate finance. At its current consolidated market cap of $2.02 trillion, SpaceX maintains its position above Saudi Aramco, which is currently valued at approximately $1.70 trillion. This valuation divergence highlights what global capital allocators are willing to pay for forward-looking operational capacity versus current physical cash generation.
Analyzing the saudi aramco vs spacex market cap dynamics reveals an intense debate over corporate fundamentals. Saudi Aramco produces steady, multi-billion-dollar quarterly net net profit margins supported by global energy demands. Conversely, SpaceX is valued on its near-monopoly over commercial satellite deployment, military defense launch contracts, and future interplanetary infrastructure. This premium creates a wider valuation spread, leaving the stock more exposed to short-term pullbacks when macroeconomic liquidity tightens.
Market Structures and the Nasdaq SPCX Closing Price First Week
During its first five days of public trading, the asset demonstrated standard patterns associated with high-profile listings. The nasdaq spcx closing price first week settled at a premium relative to its initial $135 offering price, holding structural support above $150 despite extensive profit-taking from early venture equity participants. This initial floor was partially reinforced by institutional indexing expectations, as passive asset managers adjusted their systemic models.
Nasdaq equity research teams confirmed that under expedited listing protocols, SPCX will officially join the Nasdaq 100 index on July 7, 2026. This fast-track regulatory inclusion is projected to trigger an estimated $7.3 billion in non-discretionary corporate buying from exchange-traded funds (ETFs) and index-tracking mutual funds. This impending baseline demand altered institutional order routing during the first week, preventing a deeper breach of the initial IPO pricing floor.
Quantitative Analysis of Capital Returns and Corporate Valuations
Evaluating the long-term sustainability of the largest tech initial public offering returns requires checking traditional valuation metrics against high-growth realities. Independent research notes highlight that the company operates at an elevated premium compared to traditional industrials. According to a research brief from Morningstar published after the debut, “the stock is trading at a 152% premium,” leading the firm to establish a conservative “fair value of $62 on the stock as of June 16.”
This conservative framework is driven by a trailing price-to-sales (P/S) ratio that reached 78 during peak June trading, contrasting sharply with traditional technology giants like Nvidia, which historical averages place closer to 19 times sales. The divergence between fundamental equity value and speculative market pricing is a standard characteristic of historic tech offerings. Investors backing these listings routinely prioritize absolute dominance in an emerging vertical over current quarterly price-to-earnings metrics.
Structural Alignment of Aerospace Sector Equity Valuation Multiples
The public floating of SpaceX has fundamentally disrupted how investment banks calculate aerospace sector equity valuation multiples. Historically, aerospace defense primitives like Lockheed Martin, Northrop Grumman, or Boeing traded on predictable enterprise-value-to-EBITDA (EV/EBITDA) multiples ranging between 12x and 18x. The integration of high-margin telecommunications infrastructure via the Starlink constellation has forced a hybrid valuation model.
Traditional Aerospace Valuation Framework:
[Predictive Defense Contracts] ---> 12x - 18x EV/EBITDA Multiples

Modern Hybrid Space Technology Framework:
[Launch Operations] + [Global Satellite Broadband] ---> 75x+ Forward P/E or Elevated P/S Multiples
This hybrid approach blends capital-intensive hardware metrics with high-margin software-as-a-service (SaaS) multiples. Because Starlink generates more than 60% of the firm’s consolidated top-line revenue, investment committees are applying software recurring revenue models to a business that physically builds large-scale rocket boosters. This structural shift has inflated the implied valuation of smaller, privately held space startups aiming for secondary listings down the road.
Changing Patterns in Institutional Investment Space Technology Stocks
The composition of the SPCX shareholder registry indicates a broader shift in how institutional portfolios handle alternative aerospace assets. Previously, institutional investment space technology stocks were confined to specialized venture capital vehicles or highly restricted private placements. The presence of a highly liquid, multi-trillion-dollar public asset allows sovereign wealth funds, pension systems, and university endowments to build direct exposure.
Simultaneously, the corporate debt markets are actively testing the company’s financial leverage boundaries. Concurrent with its equity listing, the company priced a massive $25 billion corporate bond offering to fund its deep-space vehicle manufacturing facilities. While the debt sale initially attracted $90 billion in institutional demand, secondary fixed-income markets showed softer trading. A Bloomberg fixed-income report noted that the newly issued debt had “racked up paper losses of around $305 million” in subsequent trading sessions, emphasizing institutional caution over long-term capital expenditure commitments.
Technical Context and Tech Stock Market Correction Patterns
The sudden contraction from the asset’s post-IPO high aligns cleanly with documented tech stock market correction patterns. Historically, when a massive corporate entity lists during a period of high market concentration, it frequently draws liquidity out of peripheral technology stocks before experiencing a secondary correction of its own. This price action matches the early public behavior of historical tech market leaders, which frequently experienced initial drawdowns ranging from 20% to 30% within their first 45 days of public trading.
Typical Post-IPO Trading Pattern:
Initial Pricing ($135) -> Post-Debut Peak ($225.64) -> Secondary Drawdown ($153.23) -> Index Inclusion Stabilization
This correction pattern is further amplified by systematic shifts in the artificial intelligence and advanced chip sectors. Because the company positions its satellite data processing networks as an essential element of decentralized AI infrastructure, its equity has become highly correlated with broader semiconductor and automation indices. When those adjacent tech sectors cooled in mid-June, systematic algorithmic trading programs automatically reduced exposure to SPCX, accelerating the velocity of its initial weekly drawdown.
Real-World Consequences for the Space Industrial Base
Human Capital and Job Creation Effects
The transition from a closely held private company to a highly visible public asset introduces direct operational changes for the domestic aerospace workforce. The company employs over 15,000 workers across primary manufacturing installations in Texas and California, alongside launch complexes in Florida. The shift toward public quarterly reporting forces a stricter focus on near-term margins, altering employee equity incentive structures that were previously tied to periodic internal private tender offers.
Global Supply Chain Dynamics
The massive $85.7 billion capital infusion from the IPO is targeted directly at scaling production lines for both the Starship launch platform and next-generation satellite arrays. This capital deployment creates a substantial secondary economy for precision machining, advanced metallurgy, and specialized electronics suppliers across the United States. However, if the spcx share price post ipo drawdown persists over multiple quarters, it could prompt corporate leadership to optimize capital expenditure budgets, potentially slowing down order volumes for smaller subcontractors.
What the Numbers Show: Financial Stability Under Scrutiny
From an operational standpoint, the financial filings submitted to the Securities and Exchange Commission show an enterprise navigating significant capital consumption. While the Starlink satellite segment achieved operational profitability, the heavy development costs of the deep-space transportation division continue to generate substantial cash outflows. This mix of high-margin commercial services and long-term development projects creates a unique corporate profile.
The upcoming July 7 index inclusion will serve as a key structural test for the stock’s stability. While passive index fund buying will provide a predictable wave of demand, the long-term trend depends on the company’s ability to hit its targeted launch schedules and grow its commercial broadband user base. For global markets, the performance of SPCX remains a clear barometer for investor appetite for high-risk, capital-intensive technology investments in a changing macroeconomic environment.
Stay sharp with Ongoing Now!
—
Source and Data Limitations: The analysis presented in this corporate profile relies on public financial disclosures, including recent registration statements and historical listings data from the Securities and Exchange Commission (SEC) through June 2026. Additional market data, closing prices, and index inclusion details are sourced from Nasdaq OMX group, Bloomberg financial summaries, and published equity research reports from Morningstar and The Motley Fool dated June 16 through June 27, 2026. This article excludes unverified social media speculation regarding private corporate valuations or unannounced government contracts. All corporate financial metrics and market caps are subject to standard end-of-quarter auditing revisions and exchange adjustments.